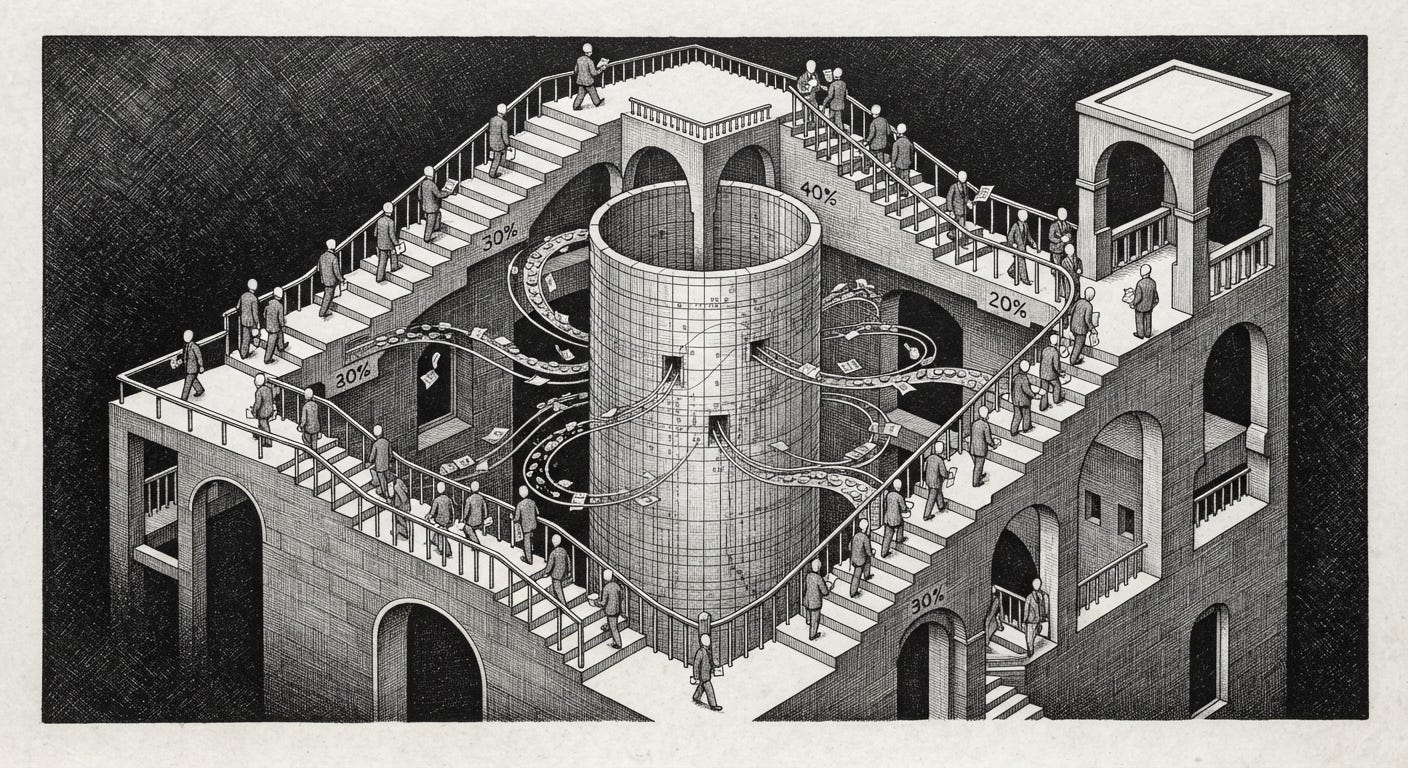
"It should be clear that modern fractional reserve banking is a shell game, a Ponzi scheme, a fraud in which fake warehouse receipts are issued and circulate as equivalent to the cash supposedly represented by the receipts." — Murray N. Rothbard, The Mystery of Banking
That quote is not a perfect description of index funds. Index funds do not create new shares of Apple or Nvidia out of thin air. But they do share something with fractional-reserve banking: both are part of systems in which financial claims and valuations can grow faster than the underlying production, both depend on belief, and both become vulnerable when that belief begins to falter.
Go find your retirement statement. Look at the total. For most people, it represents the largest single asset they own.
But what is it, really? It’s a claim—a claim on future earnings and production, much of it generated by people who are not yet born.
And a claim rests on belief. What you are really counting on is that millions of strangers will continue to believe in the value of the same assets you own.
To understand why belief is all that holds it up, we have to go back to 1694.....
https://wendywilliamson.substack.com/p/passive-ponzi
When the Bank of England was founded, England was the world’s rising power. It was producing, conquering, and accumulating. The chain of belief was anchored in real production: the English economy could actually produce what the government promised to pay.
Three centuries later, the financial center of gravity has moved. Bretton Woods in 1944 formalized the transition from London to New York, from the pound to the dollar. The United States became the world’s banker, the issuer of the reserve currency, the center of the financial universe.
But something else happened along the way. America has run a trade deficit every year since 1976. It has accumulated net foreign debt of roughly $21 trillion—approximately 70 percent of GDP, the largest net foreign debt of any advanced economy. It no longer produces what it consumes. It imports. It no longer saves what it invests. It borrows. It no longer exports what it owes. It prints.
The 1694 template created a system that could borrow against future production. The United States has gone further. It borrows against the production of other countries. It consumes what China, Germany, and Japan produce. It finances its deficits with the savings of foreigners. It has become the world’s largest debtor, and its creditors are the nations it once sought to contain. The question is what happens when the chain of belief that sustains this arrangement starts fading.
The same forced-flow mechanism operates at the sovereign scale. Foreigners recycle their trade surpluses into U.S. assets—Treasury bonds, agency debt (bonds issued by government-sponsored enterprises like Fannie Mae and Freddie Mac), equities—because the dollar system requires a destination for their reserves. The inflows that hold up the bond market are the same inflows that hold up the stock market. The passive investor and the foreign central bank are both buying because the system channels them into buying.
The chain of belief runs from the 401(k) in Ohio to the reserve manager in Beijing, and neither is making a judgment. Both are following a flow.
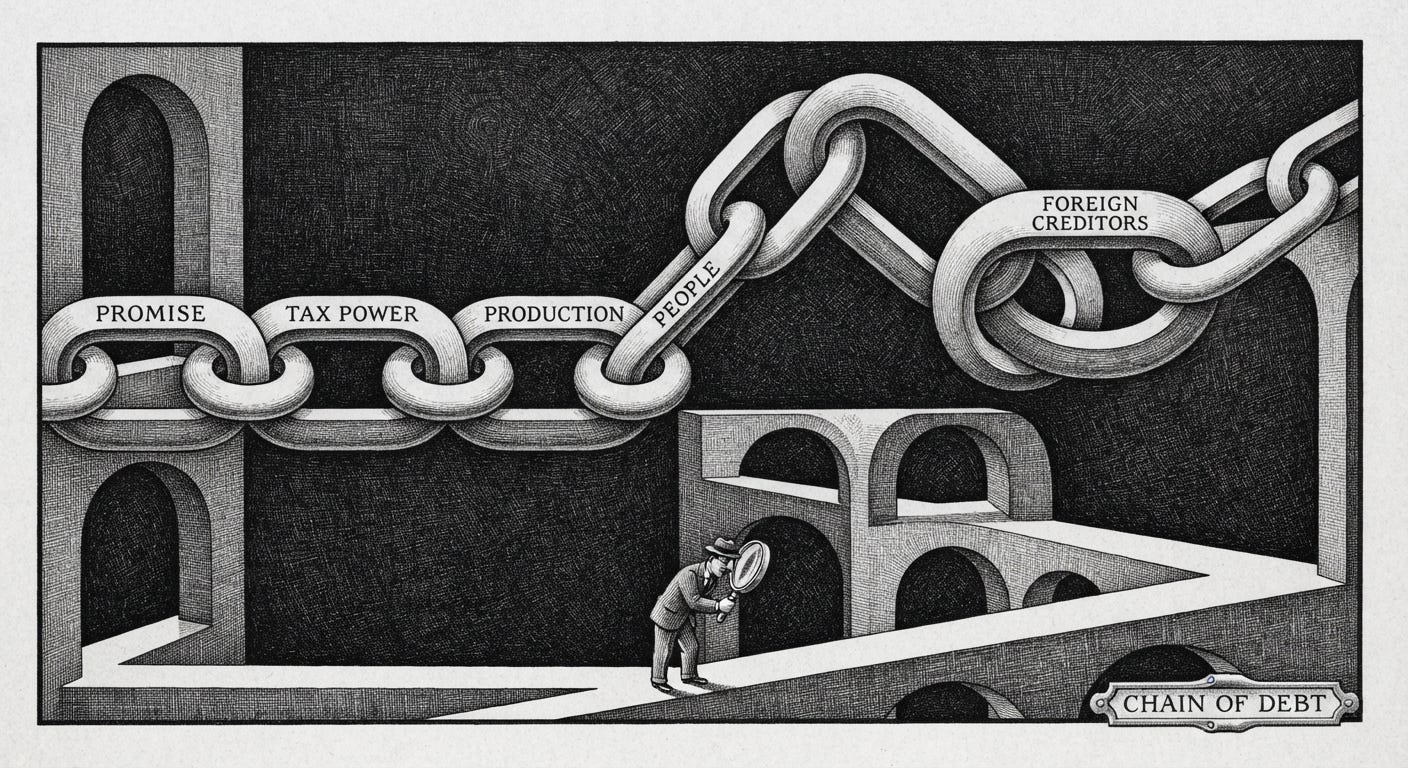
This is the inversion, completed. The chain of belief that once ran from the banknote to the government’s promise to Parliament’s taxing power to the English economy to the English people has now been stretched across oceans and continents. The first link—the promise—is still there. The middle links—the tax power, the economy—have been hollowed out. The final link—the people—are no longer producers. They are consumers, financed by the production of others.
The 1694 inversion has run for over three centuries. It has survived wars, depressions, and the collapse of empires. It has survived because it is not a bubble in the conventional sense. It is a permanent bubble—a self-reinforcing loop of debt, belief, and state power with no natural exit.
But the extreme produces its opposite. The longer a one-sided tendency dominates, the more violent the reversal. Every dependency the United States has accumulated—on foreign production, on foreign savings, on foreign belief in the dollar—is a link in the chain of belief. Every one of them depends on trust.
When that trust falters—when foreign creditors question whether they will be repaid, when domestic investors realize that their retirement accounts are claims on production that may not materialize, when the flow of passive capital reverses and the fire door proves too narrow—the chain will break.
The prediction is not a date. It is a direction. The belief that claims on the future can function as wealth will produce its opposite. Not because someone is plotting. Not because the system is evil. Because the one-sidedness of the inversion cannot hold.
The correction will not be an event. It will be a process—a slow recognition that the claims cannot all be settled, followed by a faster one. That process is already underway.
The 1694 template is not eternal. It is a historical arrangement, built on a specific set of beliefs, sustained by a specific set of institutions, anchored in a specific set of production relationships. When those relationships change—when the production moves, when the trust erodes, when the flows reverse—the template changes with them.
The future is not a ledger entry. It is the farm producing next year’s harvest. The factory producing tomorrow’s goods. The energy that powers the machine. The worker who shows up. The trust that makes a contract meaningful. The natural world that supplies what the system ultimately consumes.
The machine has forgotten this. It has treated the ledger as the territory. It has treated claims on production as production itself. It has treated the savings of foreigners as its own wealth.
That is what you are holding when you hold your retirement statement. Not wealth. A claim—on production that has not yet happened, held aloft by the belief of millions of strangers.
What you think you own is a claim on continued inflows. When the inflows stop, the claim stops being wealth. It becomes a line in a ledger.
And a line in a ledger is not the world. The world is still here, waiting to be seen.